What Should You Look for in a Realtor Near Tinker AFB?The right realtor near Tinker AFB understands military PCS timelines, and knows the Oklahoma County submarkets — Midwest City, Del City,
Dated: November 20 2025
Views: 1026
With the median price of a home in Oklahoma sitting around $260,000, many first-time buyers—especially younger Oklahomans—are looking for creative ways to break into the housing market. One concept recently introduced by the Trump administration in November 2025 is the 50-year mortgage. While it may sound like a modern solution to the affordability crisis, this ultra-long loan has been used sparingly in the U.S. and abroad for decades. Before you sign up for 600 monthly payments, it is important to understand the significant trade-offs involved.
The primary draw of a 50-year mortgage is lower monthly payments. By stretching the debt over five decades instead of three, buyers can reduce their monthly mortgage payments—but are the savings significant enough?
While a 50-year mortgage can make higher-priced homes more accessible to buyers, consider the financial implications of needing to utilize such a long-term loan in the first place…
“Be honest with yourself here. If you have to take out a 50-year mortgage to lower your monthly payments, you’re definitely trying to borrow more than you should. The interest rate is also significantly high, so you’re paying a fortune in interest alone. You need to take a look at how much house you can really afford and reconsider your mortgage options.”
—ramseysolutions.com • What Is a 50 Year Mortgage?
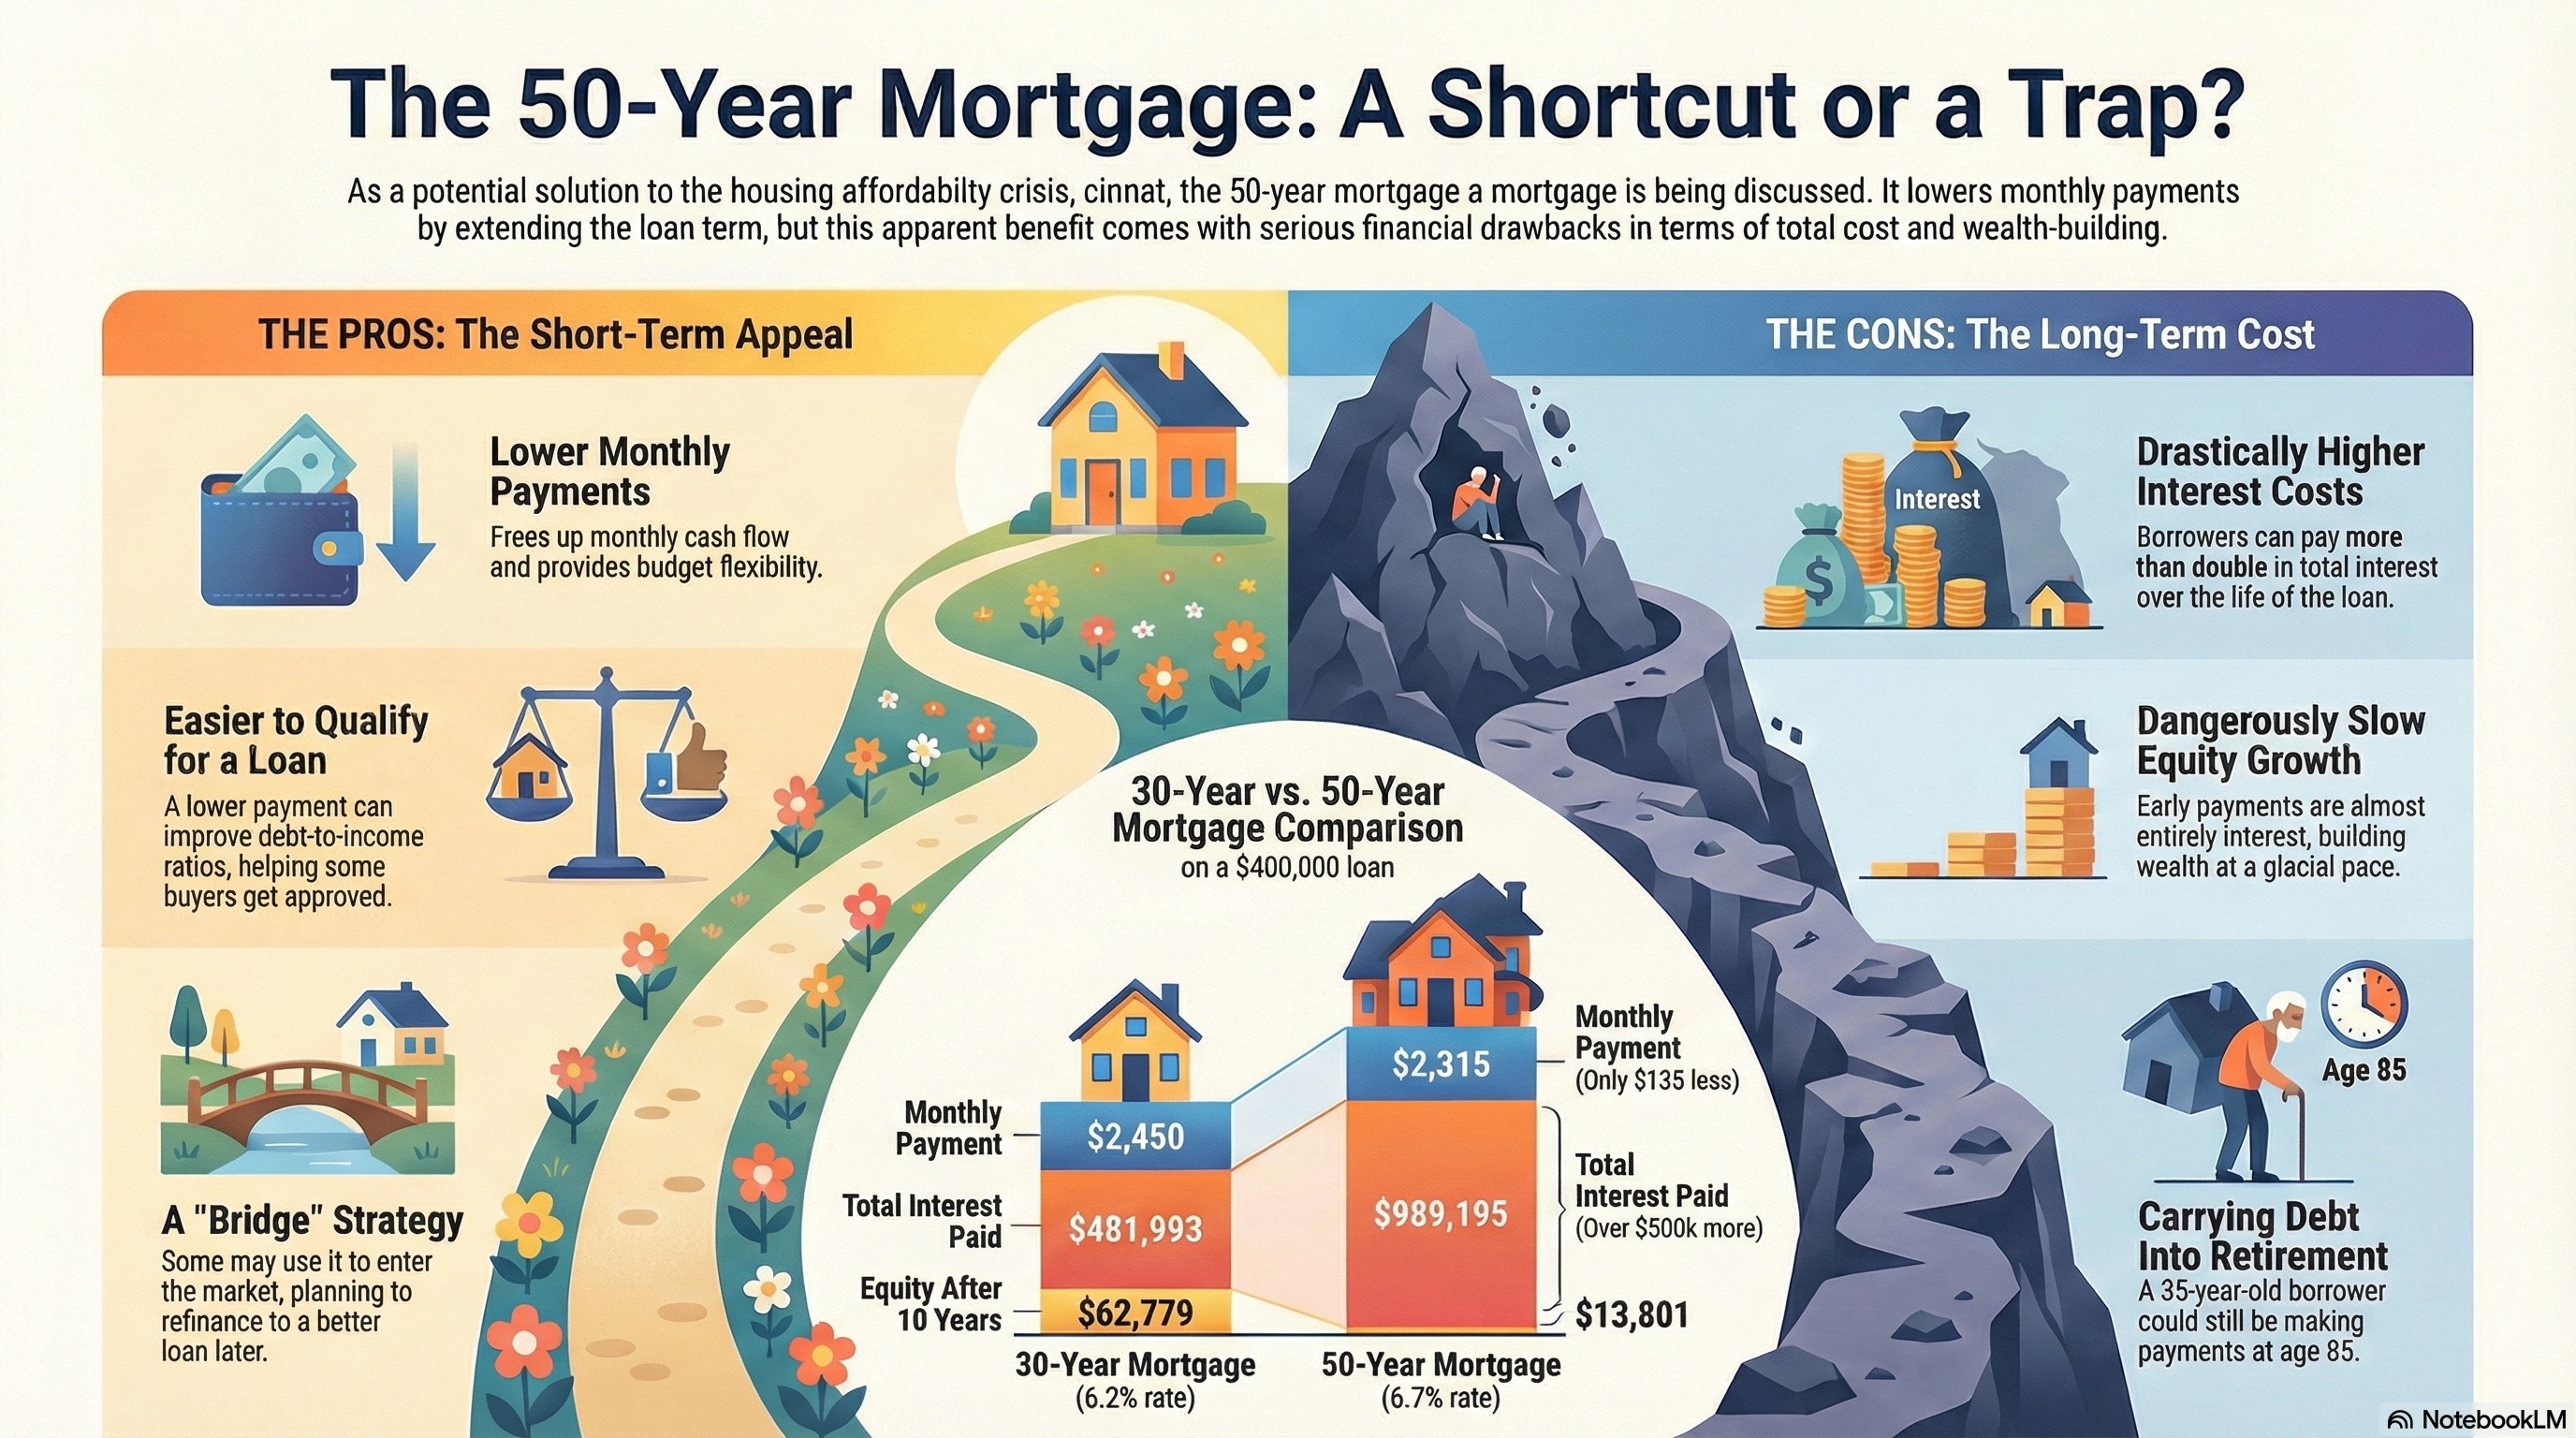
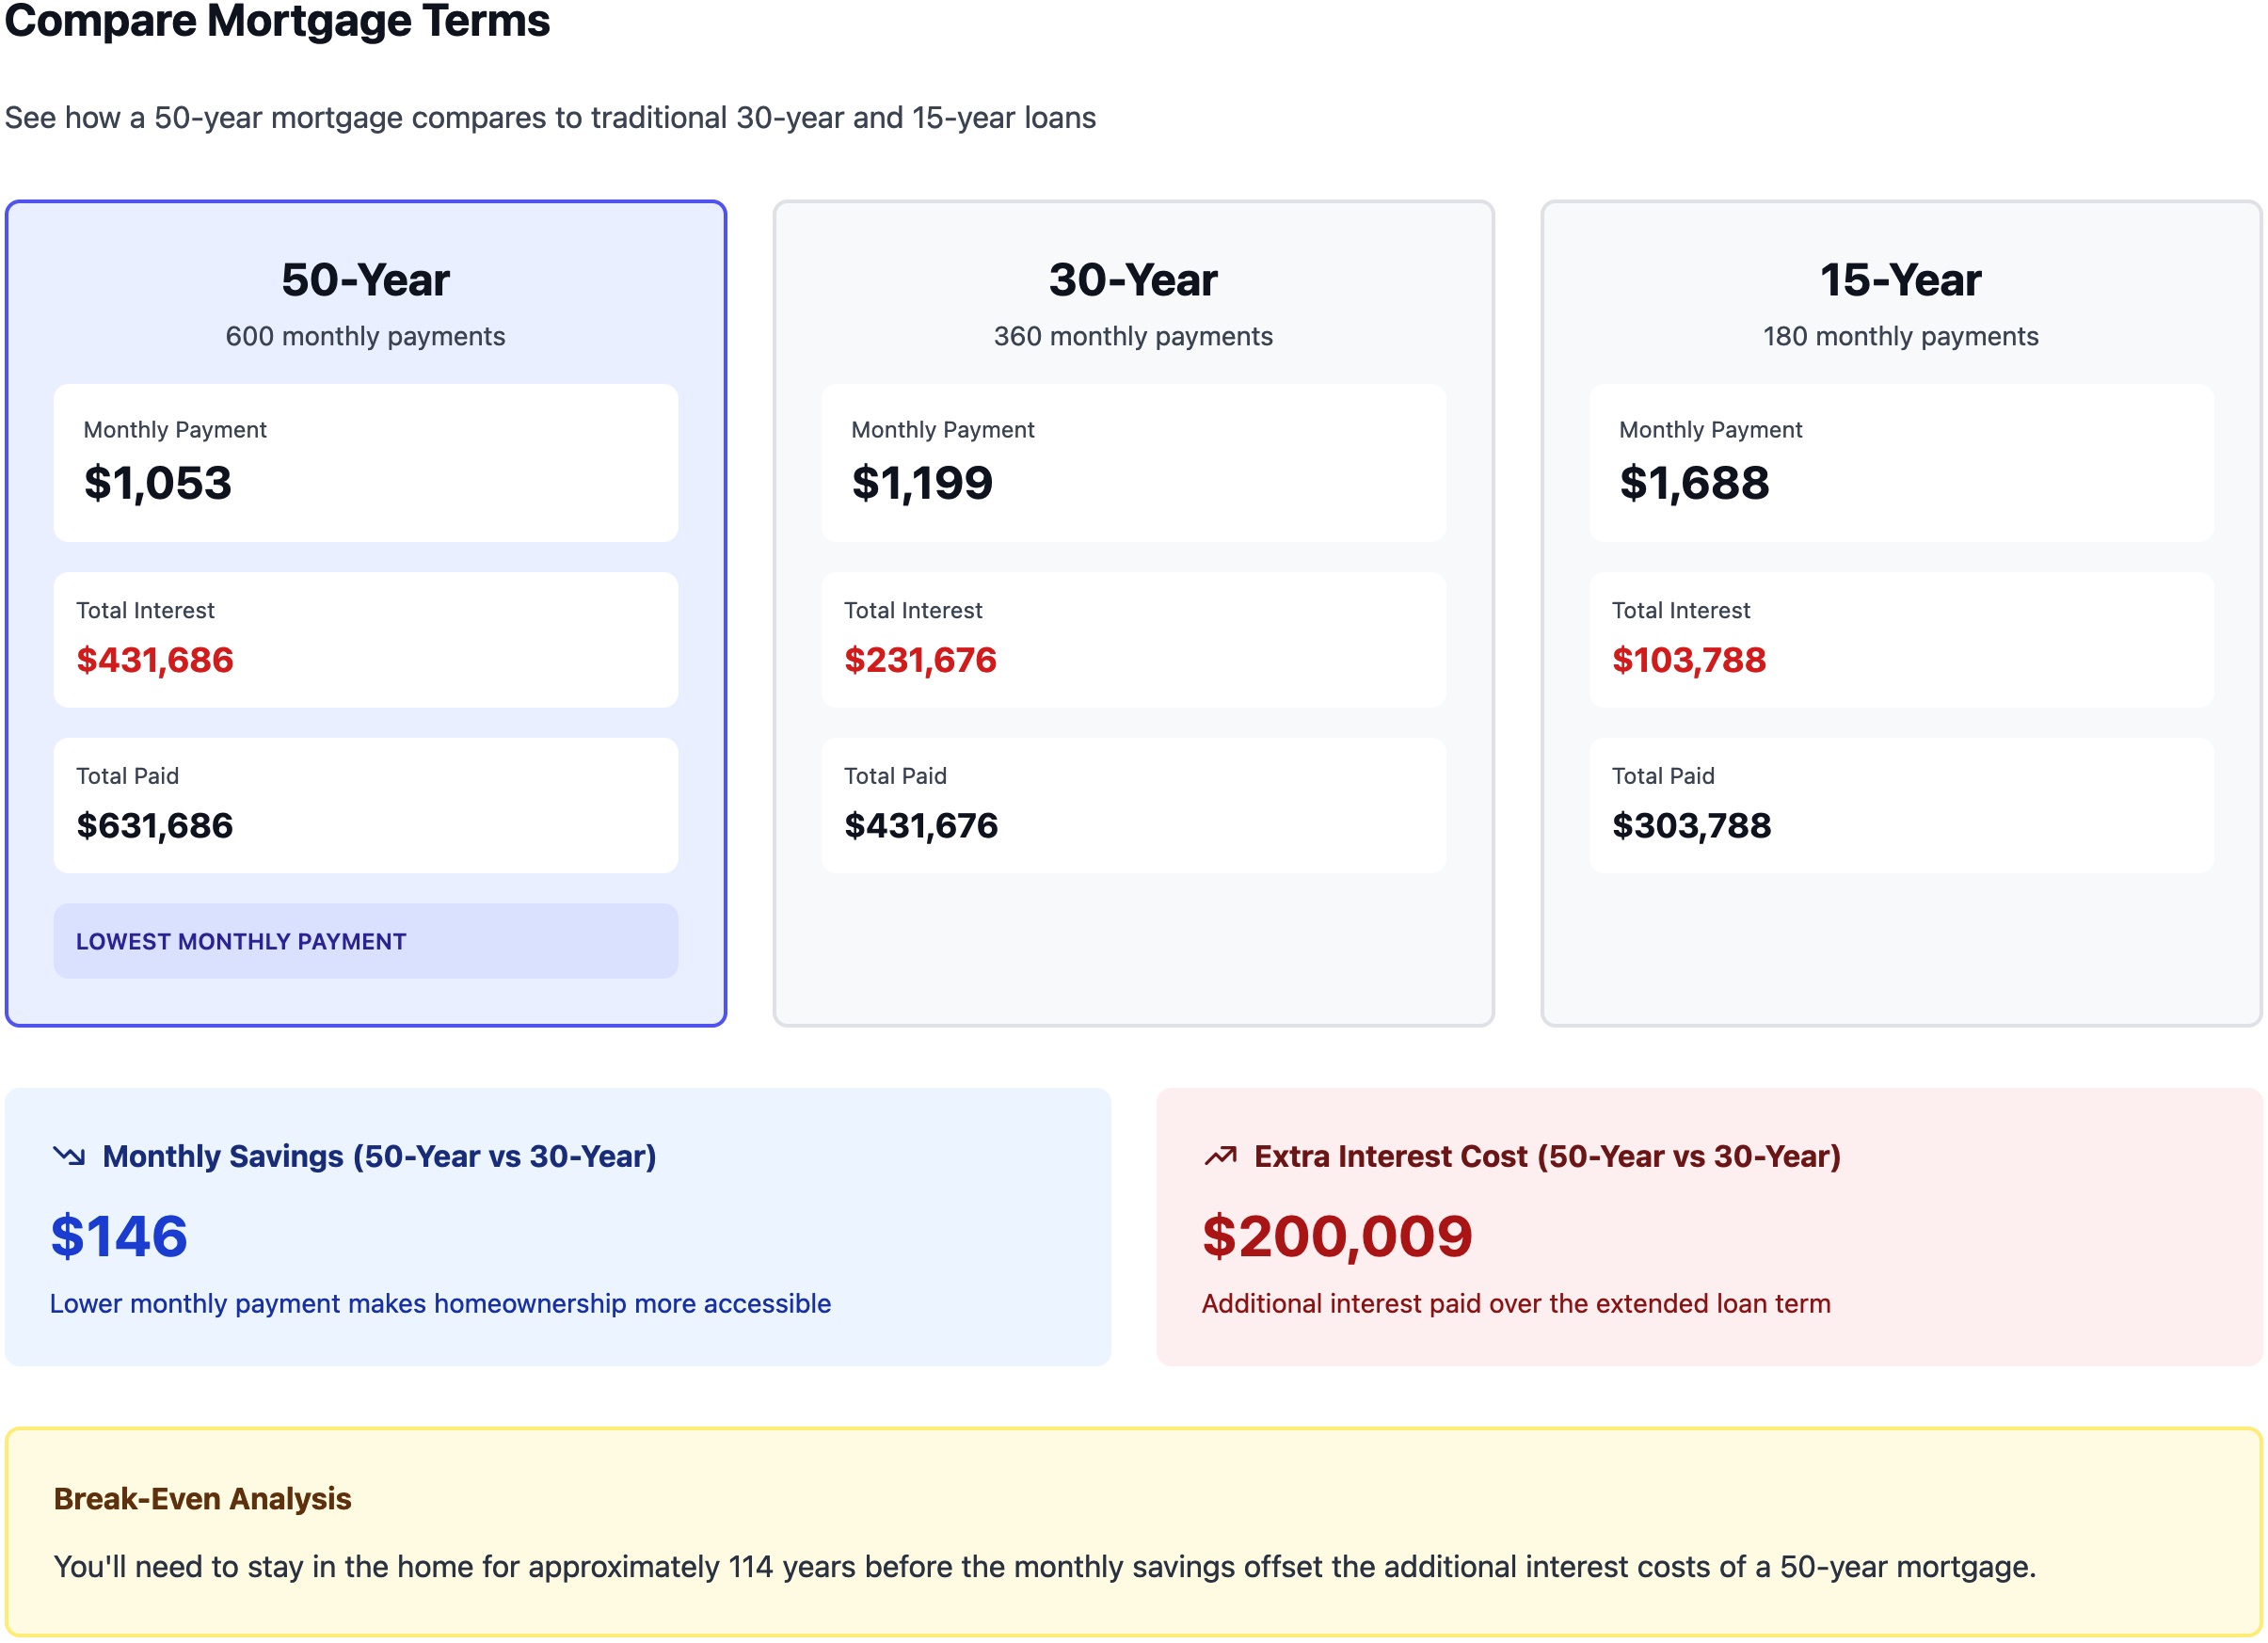
While the monthly savings may be tempting, they may not outweigh the (literal) costs over the long-term…
It is also important to note that a 50-year mortgage is not yet recognized federally as a Qualified Mortgage (QM) until approved by Congress. This is a critical distinction because a QM status provides certain protections for investors if a mortgage loan goes bad. Without this federal recognition, these loans are currently rare and may come with higher interest rates or stricter private lender requirements.
In short, the answer is “no” or in very rare and strategic situations. A 50-year mortgage is best viewed as a temporary strategic tool rather than a "forever loan". Some buyers use it to get their foot in the door today, intending to refinance into a shorter 30-year term once their income increases or debt decreases. However, this is a gamble. If home values drop or interest rates rise, you may find yourself "stuck" in a high-interest cycle.
Before making a decision, we recommend speaking with your Flotilla Real Estate Partner and their trusted lender to see how different mortgage structures align with your long-term goals.
© 2025 Flotilla Holdings, Inc.
Jennifer Cody (Arsenault) is a lifelong Oklahoman and seasoned real estate professional who has been serving her community since 1998. As the founder and Broker Associate at Flotilla Real Estate Partn....
What Should You Look for in a Realtor Near Tinker AFB?The right realtor near Tinker AFB understands military PCS timelines, and knows the Oklahoma County submarkets — Midwest City, Del City,
The Oklahoma City housing market is undergoing a noticeable shift toward a more balanced environment as we head into the fall. With a significant jump in new properties hitting the market and total
Ask a handful of REALTORS® how the housing market is doing and you’ll probably get a couple of different answers. That’s because right now, the market runs on two very different
Our obsession with Turkish culture originally started with a search for vibrant Turkish mosaic glass lamps. At the 2025 Oklahoma State Fair, our favorite lamp vendor gave us the ultimate insider:
 Copyright© 2026 MLSOK, Inc. listing content is believed to be accurate but is not guaranteed. Subject to verification by all parties. The listing information being provided is for consumers personal, non?commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested in purchasing. This listing data is copyrighted and may not be transmitted, retransmitted, copied, framed, repurposed, or altered in any way for any other site, individual
and/or purpose without the express written permission of MLSOK, Inc. Information last updated on September 22, 2026 7:26 PM UTC
© 2026 OKC Metropolitan Association of REALTORS® (OKMAR). All rights reserved.
Disclaimer: All information deemed reliable but not guaranteed and should be independently verified. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) nor September 22, 2026 7:26 PM UTC shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless.
Data last updated on September 22, 2026 7:26 PM UTC
Show More...
 MLS Technology® Oklahoma; All information deemed reliable but not guaranteed. All properties are subject to prior sale, change or withdrawal. Neither listing broker(s) or information provider(s) shall be responsible for any typographical errors, misinformation, misprints and shall be held totally harmless. Listing(s) information is provided for consumer's personal, non-commercial use and may not be used for any purpose other than to identify prospective properties consumers may be interested
in purchasing. The data relating to real estate for sale on this website comes in part from the Internet Data Exchange program of the Multiple Listing Service. Real estate listings held by brokerage firms other than Flotilla Real Estate Partners may be marked with the Internet Data Exchange logo and detailed information about those properties will include the name of the listing broker(s) when required by the MLS. Copyright ©2026 All rights reserved.
Last Updated: September 22, 2026 7:23 PM UTC
Show More...
